
By Chibuzor Alli
The Pan-African Payment and Settlement System plans to connect every African country to its cross-border payment network within the next five years as transaction volumes continue to rise across the continent.
PAPSS Chief Executive Officer, Mike Ogbalu, said the platform expects to expand from 30 countries currently to about 38 by the end of 2026, with a longer-term target of achieving about 80 per cent continental coverage.
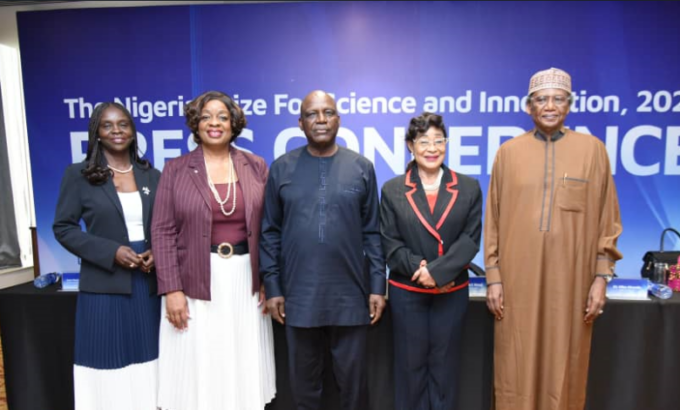
Speaking at a press conference in Lagos, Ogbalu said PAPSS ultimately aimed to bring all African countries onto the payment network, with South Africa identified as the major economy yet to join.
“We expect that by the end of those five years, we will have all countries,” he said.
According to Ogbalu, discussions with South Africa have been positive as PAPSS works to bring the continent’s major markets into a unified payment network.
The expansion comes as PAPSS enters the second phase of its strategic plan after spending its first phase establishing the infrastructure, regulatory framework and institutional connections required for instant cross-border payments.
“In phase one, we dealt with spread. But today, in our phase two, it is all about deepening, taking the value that we created and actually making it available where it matters most to the end users,” Ogbalu said.
PAPSS currently connects 30 countries, about 26 central banks and more than 200 financial institutions. The system also links with national and regional payment switches, allowing banks, fintechs and payment service providers to access its cross-border payment infrastructure.
PAPSS transaction volumes surge
The payment platform has recorded significant growth in activity, with transaction volumes increasing by more than 1,000 per cent year-on-year as adoption accelerates, particularly among smaller businesses.
Ogbalu said banks that had integrated PAPSS into their digital banking channels had also recorded three- to fourfold increases in transaction volumes.
He said the trend indicated growing movement away from cash and branch-based transactions as businesses and consumers increasingly use digital payment channels.
The next phase, according to Ogbalu, will focus on converting the infrastructure already established into greater usage for remittances, merchant payments and other cross-border transactions.
PAPSS seeks wider business adoption
PAPSS is also using application programming interfaces to allow businesses and payment providers to connect to accounts on the network through a single interface.
The approach could simplify cross-border payments for businesses operating across different African markets.
However, the platform faces regulatory and infrastructure differences between countries, with central banks moving at different speeds in connecting their domestic payment systems.
“Different central banks move at different paces. They have an understanding of the value that we create differently, and therefore some of them take a bit of time,” Ogbalu said.
He said PAPSS was addressing concerns over control of domestic payment infrastructure by positioning the platform as a connecting layer rather than a replacement for existing national payment systems.
“We have said to them that if you like your payment system, keep it, but connect it into PAPSS,” he said.
PAPSS and AfCFTA
The expansion of PAPSS is central to the payment infrastructure requirements of the African Continental Free Trade Area, which seeks to increase trade among African countries.
Ogbalu said the second phase would focus on turning the infrastructure already built into greater commercial activity across the continent.
“We focused more on the building. This phase two now is more about how we actually begin to deliver on the promises of AfCFTA and Agenda 2063,” he said.
With PAPSS seeking to expand its reach to every African country, the platform’s next challenge will be converting wider connectivity into sustained transaction growth and greater use by businesses and consumers involved in cross-border trade.




Leave a comment