
By Chibuzor Alli
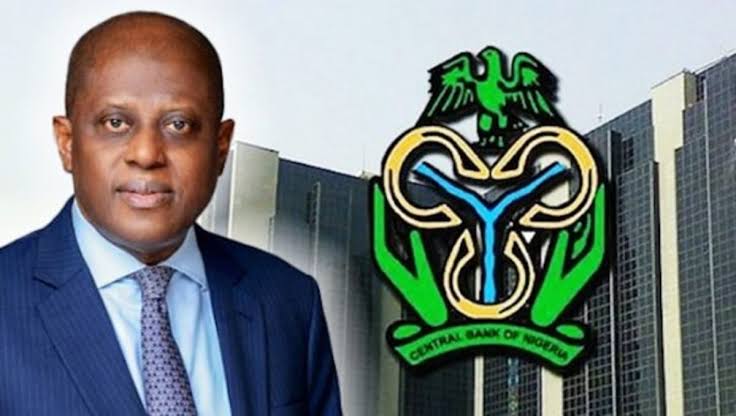
Three years after Olayemi Cardoso took charge of the Central Bank of Nigeria, the country’s monetary landscape looks markedly different from the one he inherited — but the gains have come with substantial costs, and the durability of the reforms is now being tested.
Cardoso’s tenure has been defined by three broad objectives: restoring the CBN to a more conventional monetary-policy role, reforming the foreign-exchange market and rebuilding confidence in Nigeria’s financial system.
The latest decision by the Monetary Policy Committee to cut the Monetary Policy Rate by 350 basis points to 23% offers a useful marker for assessing that journey.
After one of the most aggressive tightening cycles in recent Nigerian history, the CBN is now attempting to lower the cost of money without reopening the imbalances that prompted the tightening in the first place.
The bank has also retained high cash reserve requirements, suggesting that the rate cut is intended as an adjustment to monetary-policy transmission rather than a wholesale abandonment of liquidity controls. The CBN described the move as an “operational reset” designed to strengthen the signalling role of the MPR and support the transition towards inflation targeting.
That transition is arguably the central theme of Cardoso’s three years.
From intervention to orthodox monetary policy
When Cardoso assumed office, the CBN was operating in an environment marked by multiple exchange rates, substantial foreign-exchange obligations, elevated inflation and large central-bank interventions.
The governor has repeatedly argued that the bank needed to return to its statutory mandate of maintaining monetary and financial stability rather than using quasi-fiscal interventions to address problems that should ordinarily sit elsewhere in government.
At his Senate screening, Cardoso outlined a 10-point reform agenda that included compliance with the CBN Act, stronger corporate governance, an exit from quasi-fiscal activities, improved payment systems, wider access to credit, financial inclusion and efforts to strengthen foreign reserves.
The subsequent policy direction broadly reflected that agenda.
The CBN moved to unify the foreign-exchange market, removed restrictions on access to FX for the importation of 43 items and began clearing accumulated FX obligations.
The bank says the reforms reduced distortions and improved transparency in the market. According to the CBN, about $7bn in verified FX obligations were cleared, while external reserves rose from $33.6bn in October 2023 to $37.9bn by July 2024.
The reforms also represented a major shift away from attempts to administratively manage the exchange rate.
That shift, however, came with a substantial initial depreciation of the naira.
For households and businesses whose costs were already rising, the adjustment was painful. Imported goods became more expensive, while manufacturers faced higher costs for raw materials, machinery and other inputs.
The key question therefore is not simply whether the FX market became more transparent, but whether the resulting market has become sufficiently stable and liquid to support investment and production.
Three years into the experiment, there are signs of improvement.
The reserve story is one of Cardoso’s strongest measurable gains
Nigeria’s external reserves have become a significant buffer during Cardoso’s tenure.
As of 18 September 2026, gross external reserves stood at $55.25bn, according to the CBN, the highest level in 18 years and equivalent to about 11.3 months of imports.
The improvement has been accompanied by stronger external balances.
The CBN reported that Nigeria recorded a $3.51bn balance-of-payments surplus in the second quarter of 2026, up from $2.38bn in the first quarter. The current-account surplus also increased from $4.49bn to $7.54bn.
Cardoso has attributed part of the strengthening external position to higher diaspora remittances and the broader consistency of the policy framework.
This matters because reserves provide the CBN with greater room to manage episodes of FX pressure.
But reserves alone do not establish that the exchange-rate reforms have solved Nigeria’s structural FX problems.
The naira remains exposed to oil-price movements, portfolio flows, import demand and domestic inflation. The recent reduction in interest rates will therefore provide an important test of whether the improved external position can withstand potentially weaker incentives for foreign portfolio investors.
That test has become particularly relevant as Nigeria moves into a lower-rate environment.
The cost of fighting inflation
If FX reform has been one pillar of Cardoso’s tenure, aggressive monetary tightening has been the second.
The CBN raised the MPR repeatedly during the tightening cycle, eventually taking it to 27% before beginning a gradual reduction.
The strategy was straightforward: make money more expensive, restrict excess liquidity and use higher interest rates to bring inflation under control.
The consequences were equally straightforward.
Borrowing became more expensive.
Businesses faced higher financing costs at precisely the time that they were dealing with higher energy, logistics, imported-input and FX costs.
Manufacturers, small businesses and other credit-dependent companies were particularly exposed.
CBN research has previously identified a negative relationship between lending rates and manufacturing output, reinforcing the argument that prolonged high borrowing costs can restrict productive activity.
The problem for the central bank was that inflation was not being driven solely by excess demand.
Supply constraints, food prices, exchange-rate movements, energy costs and structural weaknesses all played important roles.
That meant monetary tightening could influence demand and expectations, but could not by itself repair roads, increase food production, fix gas pipelines or reduce electricity costs.
This is one of the fundamental limitations of Cardoso’s reform programme: the CBN can influence the financial conditions surrounding the economy, but many of Nigeria’s most important inflationary pressures originate outside monetary policy.
The 2026 rate cut marks a new phase
The September 2026 rate cut to 23% therefore represents more than cheaper money.
It is a test of whether the CBN believes the foundations established during the tightening period are strong enough to permit a less restrictive policy stance.
The MPC also recalibrated the standing facilities corridor to +50/-300 basis points around the MPR, placing the transaction corridor between 20% and 22.5%.
At the same time, the CBN retained cash reserve requirements at 45% for deposit money banks, 16% for merchant banks and 75% for non-Treasury Single Account public-sector deposits.
The combination suggests an attempt to lower the benchmark cost of money while retaining strong control over banking-system liquidity.
For borrowers, however, the important question is not what happens to the MPR in Abuja but what happens to actual lending rates.
A commercial bank does not lend to a manufacturer at the MPR.
The final lending rate reflects funding costs, credit risk, capital requirements, operating costs, collateral and expectations about inflation and the exchange rate.
That means the success of the latest policy reset will ultimately be measured by transmission.
If lending rates remain high despite a sharply lower MPR, the benefit to businesses and households will be limited.
Banking-sector recapitalisation could reshape the system
Another major component of Cardoso’s tenure has been the banking-sector recapitalisation programme.
In March 2024, the CBN announced new minimum capital requirements of N500bn for commercial banks with international authorisation, N200bn for banks with national authorisation and N50bn for regional banks.
The argument behind the policy is that a larger capital base should give banks greater capacity to absorb shocks, finance larger transactions and support a growing economy.
But recapitalisation also changes the competitive structure of the banking sector.
Banks that cannot independently meet the new requirements may need to raise fresh capital, merge, acquire other institutions or reconsider their business models.
The programme is therefore not simply about making banks bigger. It is also about determining what kind of financial system Nigeria wants to operate as the economy expands.
Payments and financial infrastructure have also changed
Cardoso’s tenure has extended beyond interest rates and FX.
The CBN has continued to reform Nigeria’s payments infrastructure, financial regulation and digital financial services.
In 2026, the bank introduced new measures affecting instant payments, BDC participation in the foreign-exchange market, anti-money-laundering systems and the broader payments ecosystem.
The CBN also unveiled Payments System Vision 2028, presenting it as a framework for developing a more inclusive and digitally driven payments system.
These reforms receive less public attention than the naira or MPR because their effects are gradual.
Yet they could prove important over the longer term because efficient payments reduce transaction costs, improve financial inclusion and make it easier for formal businesses and consumers to participate in the financial system.
Cardoso has also pulled the CBN back from quasi-fiscal activity
Perhaps the least visible but most consequential part of the reform agenda has been institutional.
Cardoso inherited a central bank that had become deeply involved in financing and intervention programmes.
He has argued that the scale of those activities contributed to excess liquidity and complicated monetary-policy management.
At his recent anniversary assessment, he cited Ways and Means exposure of about N23.7tn, alongside more than N10tn in interventions, as part of the legacy conditions his administration confronted.
The attempt to return the CBN towards its traditional role has therefore been as much about institutional boundaries as interest rates.
The challenge is that quasi-fiscal programmes often emerged because other parts of the economic system were unable to solve particular problems.
Removing the CBN from those activities may improve monetary-policy discipline, but it does not automatically eliminate the underlying development problems that those interventions were intended to address.
The FX reform remains the biggest test
Of all Cardoso’s policies, the foreign-exchange reform probably carries the largest consequences.
The old system produced multiple rates and substantial opportunities for arbitrage.
The new framework is more market-oriented and transparent.
The CBN itself says the previous multiple-rate arrangement created distortions and that losses associated with the system amounted to about 3% of GDP.
But market-based pricing also means Nigerians must confront the underlying scarcity of foreign currency rather than having that scarcity partially concealed through administrative rates.
The reform therefore shifts the question from “what is the official exchange rate?” to “how deep, liquid and credible is the FX market?”
Recent reserve accumulation and improved external balances provide a stronger foundation than Nigeria had in the early part of Cardoso’s tenure.
But the durability of that foundation will depend on whether foreign-exchange supply continues to improve and whether inflation falls enough to restore the naira’s purchasing power.
Has the policy produced growth?
This is where the assessment becomes more complicated.
Cardoso’s reform programme has produced measurable changes in monetary and financial-market conditions: a reworked FX regime, higher reserves, recapitalisation rules, a stronger emphasis on inflation targeting and an attempt to reduce the CBN’s quasi-fiscal footprint.
But monetary stability and economic welfare are not the same thing.
For ordinary households, the most visible economic indicators remain food prices, electricity costs, transport costs, rents and employment.
For manufacturers, the relevant measures include the cost and availability of credit, electricity, gas, imported inputs and FX.
For investors, the critical questions include currency stability, repatriation of funds and the predictability of regulation.
This distinction is important because a central bank can improve monetary architecture while households continue to feel economic pressure.
That does not necessarily invalidate the reforms. It shows the limits of what monetary policy can accomplish on its own.
What the critics are watching
The strongest criticism of Cardoso’s approach has centred on the social and productive costs of prolonged monetary tightening.
Business groups and analysts have repeatedly argued that extremely high interest rates can crowd out private investment and make expansion difficult.
The Centre for the Promotion of Private Enterprise, for example, welcomed the latest rate reduction and argued that high financing costs had constrained manufacturing, agriculture, construction and logistics. It also warned that the benefits would depend on banks transmitting lower policy rates to borrowers.
At the same time, the rate cut itself introduces a different set of risks.
A smaller interest-rate differential can reduce the attraction of naira assets to foreign portfolio investors. If capital inflows weaken or outflows increase, pressure could return to the FX market.
There is also the risk that cheaper money could increase demand for financial assets faster than underlying economic activity expands.
The CBN is therefore attempting a difficult balancing act: reduce the cost of credit without reigniting inflation or undermining exchange-rate stability.
Three years on, the CBN is moving from repair to testing
The first phase of Cardoso’s tenure was largely about repair.
The CBN sought to clean up the FX market, address inherited obligations, rebuild reserves, tighten monetary conditions and restore the central bank’s institutional focus.
The second phase has been about consolidation.
The bank has continued with recapitalisation, financial-market reforms, payments reforms and the move towards inflation targeting.
The latest rate cut suggests the beginning of a third phase: testing whether the reforms are strong enough to support a less restrictive monetary environment.
That is why the September decision matters beyond the 350-basis-point reduction.
Nigeria is effectively testing whether the stability accumulated over the past three years can survive cheaper money.
The CBN now has a much stronger external buffer than it had at the beginning of Cardoso’s tenure. Reserves at $55.25bn and stronger external-account balances provide a materially different starting position for monetary policy.
But the unresolved questions are equally significant.
Will lower policy rates actually translate into cheaper bank loans?
Will inflation continue to moderate?
Can the naira remain stable if foreign portfolio flows weaken?
Will banks raise enough capital to support stronger lending without increasing systemic risks?
And can monetary reforms translate into stronger investment and productivity when Nigeria’s structural constraints remain?
Those questions will determine the longer-term significance of Cardoso’s three years at the CBN.
For now, the record is neither simply a story of success nor one of failure. It is a story of a central bank that has undergone a substantial policy and institutional reset, with measurable improvements in some financial indicators and significant costs and unresolved challenges elsewhere.
The latest rate cut is the clearest indication yet that Cardoso believes the repair phase has progressed far enough for the CBN to begin testing the economy’s ability to operate with cheaper money.
The results of that test may ultimately become the most important measure of his tenure.


Leave a comment